Tag Archives: JBS

Brodie’s Hobby

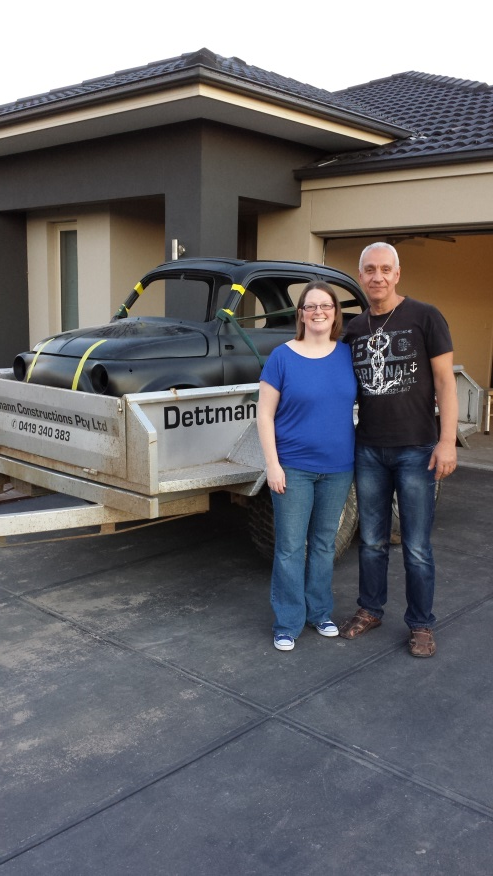
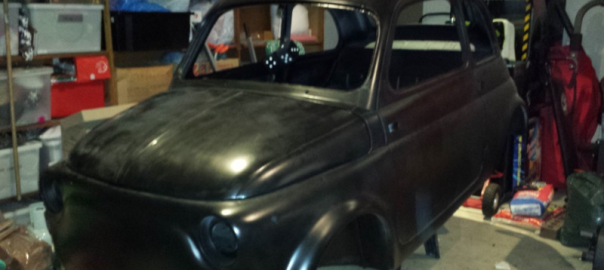
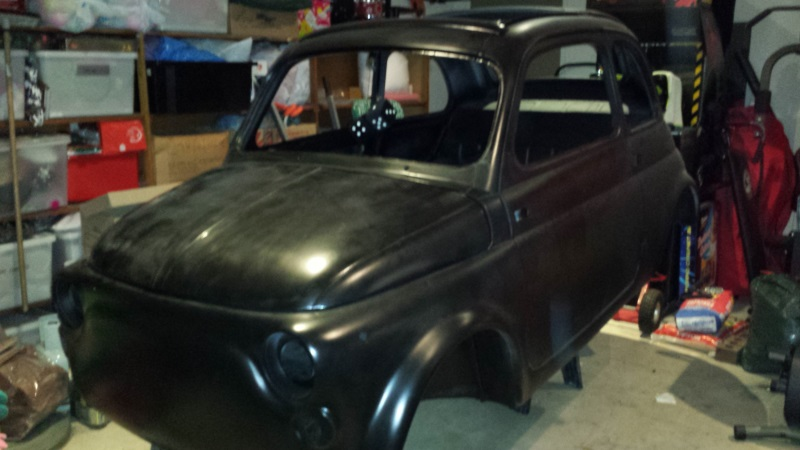
1Everyone needs a hobby and mine is a tiny little Italian. I have a 1960 Fiat 500 that I am very slowly restoring (or destroying if you talk to those in the Fiat club as I’m not really going original). I love cars and I love working on them. I’m not sure I’m actually any good or know anything that I’m doing at all but I play around, take nuts and bolts off and hope they all go back on.2

After getting a couple of quotes on welding work required that resembled Linda Evangelista’s weekly pay packet (google it for the young ones), I thought my Fiat dream was dead, until I met a lovely man who was a sucker for a lady into her car. Nick agreed to complete the welding on my little beauty for a reasonable price but wanted a year to fit it in around other projects. We fast forward to a year later and my husband is smiling again as he had been able to use the garage for 12 months and I’m smiling because I got my car back. When it left, the panels resembled a colander but now they are hole free and smooth.

Now that it looks more like a car, I’m getting more and more excited. I have most of the parts, including an upgraded engine but I’ve now got to spend the time getting everything right as I put it back together. As much as I want it done yesterday and want to be able to drive it, I also want to do a good job.
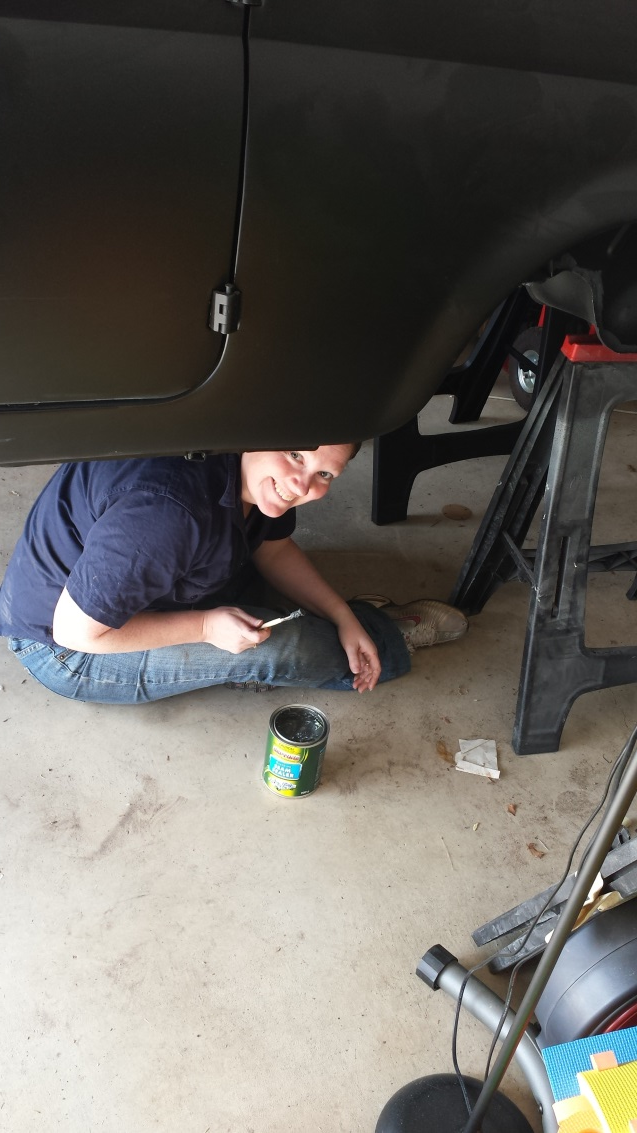
3I want to do as much as possible on the car myself. I’ve even sewn my own seat covers from leather and I stripped the car when I originally got it. The last thing I did on the car was get the seam seal out and cover all the welds. I’ve unfortunately found a broken bolt that’s welded to the car, so more welding, more parts, and more money.

Next I’ll stoneguard the bottom, then undercoat, rub back and reap before taking it to a mate’s to paint. I’m going mat black but with a gloss realistic flame over the front (see, not so original).

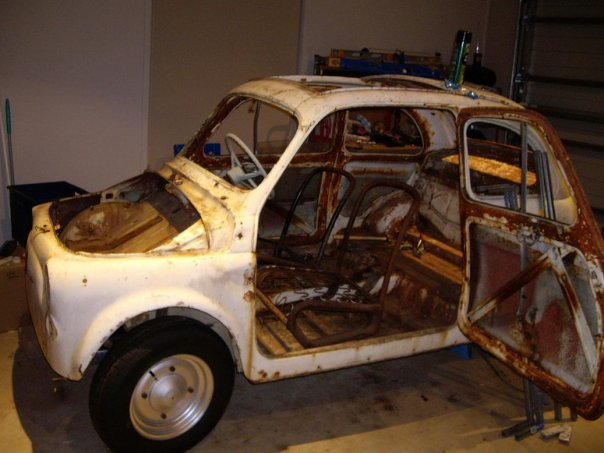
It’s coming along, especially since I bought it from a lady who had driven into her paddock 15 years earlier and never touched it again. The cows had eaten the interior and rust replaced pretty much everything else.

My biggest challenge now is the engine 4conversion. I have the newer engine (650cc instead of the 500cc, so I might hit 100 kms on a downward slope with the wind) but I need to somehow work out how to connect it to the old gearbox. It seems that it’s not as easy as the 2 page instruction sheet I downloaded off the net. So if anyone knows how I do this, I’d love the help because I really need it!


Create | Protect | Enjoy – New Income Test Rules Mean Less Age Pension

From 1st January 2015, the way account based pensions are treated under the Centrelink Income Test will change, potentially reducing your entitlements to the Age Pension.

Account based pensions have generally been given favorable treatment when Centrelink assesses your eligibility for the Age Pension.  Currently, the income counted towards Centrelink’s income test from your account based pension is the pension payments you receive less a deductible amount. This usually results in a very low amount being considered income for Centrelink purposes and as a result many people with account based pensions are able to receive valuable social security support, topping up their own pension account payments to help their retirement savings last longer.

pensionThis is set to change on 1st January 2015 when new ‘deeming’ rules come into effect for account based pensions meaning they will be subject to the same ‘deeming’ rules that apply to financial investments.  All new account based pensions will be deemed as earning a certain rate of income regardless of the actual return of the investment.  The current deeming rates are as follows:
2% p.a. on investments up to $48,000 for a single ($79,600 for a couple).
3.5% p.a. on investments over $48,000 for a single (over $79,600 for a couple)

Deeming rates are currently low by historical standards.  Any increase to the deeming rates will increase the amount of income deemed to be earned from an account based pension which will potentially reduce age pension requirements further.

If you have an account based pension opened before 1st January 2015, your account will not be subject to deeming if you are receiving Centrelink income support payments immediately prior to 1st January 2015.

If you haven’t opened an account based pension and you are eligible to do so, there may be benefits in starting an account based pension and applying for Centrelink income support prior to 1st January 2015.

Not all pensioners will be affected by these changes, as some of you will be still be assessed under the Assets Test even if the deeming provisions did apply.  If you feel you may be affected by the changes please to contact our office to discuss further.


Create | Protect | Enjoy | Insurance is a Super Benefit

Australians love being able to enjoy life with their friends and family, travel the world and drink till the sun comes up.  In order to do so we earn, save, invest, borrow and do whatever is necessary to accumulate enough funds to enjoy the finer things in life.  For a lot of Australians, taking financial risks is simply a part of everyday life; trading stocks, gambling or buying investment properties.

Today, over 80% of Australians are taking the biggest financial risk and not protecting their biggest asset, which is their own ability to earn money.  It’s relatively easy to earn it, it’s easier to burn it and apparently 80% of us think it’s too hard to protect.

In 2012, the Australian Life Insurance Industry paid out $4.4 billion in total claims.  This stat isn’t meant to highlight the fact that insurers do payout, but highlights the fact that tens of thousands of Australians in 2012 died, suffered from a terminal illness, were diagnosed with a critical illness or suffered a serious injury or illness stopping them from earning their most valued asset, income.

There are several Personal Insurance types that can assist in protecting you financially such as Life, Total & Permanent Disablement (TPD), Trauma and Income Protection.  Each serves its own purpose; to provide financial aid in the event the proverbial dung hits the fan.  Yet 80% of us think…
•    “It’ll never happen to me”, $4.4 Billion says otherwise.
•     “I’m sure it’s in my Super”, maybe, but is it enough?
•    “It’s too expensive”, where else can you get $4.4 billion?

Although Super is a convenient funding mechanism for Personal insurance it doesn’t come without its difficulties, especially at claim time.

When you hold Insurance within a suKFC Witness protectionper fund, the super trustee effectively owns your insurance and it is their responsibility to ensure any insurance payment made into the fund meets a ‘condition of release’ before they can be withdrawn from your super fund.  These conditions are set by the Superannuation Industry (Supervision) Act 1993 (SIS Act) and includes insurance claim benefits.
In the event an insurer pays out a claim, the benefits (money) are paid to the super trustee, not you or your beneficiaries.  It is then up to the trustee to determine if you meet a ‘condition of release’ before paying you the funds.  So a few legislative changes have been introduced, effective 1 Just 2014 to align and hopefully resolve the double handling of claims.

The old way:
Pre 1 July 2014, if you implemented Insurance inside a super fund, in order to get the proceeds of a successful insurance claim in your hands, you were required to satisfy two separate conditions, as mentioned above:
1.    The definitions under the insurance policy set by the insurance company to pay out the claim; and
2.    The superannuation ‘condition of release’ rules set by the SIS Act.

Unfortunately for some people who successfully claimed on their insurance, this made the process difficult.  Just because the insurance company said, “yes you can make a claim”, didn’t necessarily mean your super fund would hand over the cash.

The simple fact of the matter was a misalignment if conditions existed.  Insurers were approving claims, paying the benefits to the super trustee, but the super trustee was holding the funds inside the members super account because a ‘conditions of release’ was not met.

The new way
From 1st July 2014, the aforementioned conditions must now mirror one another, meaning that definitions of insurance policies available under super are much stricter.  They must reflect the ‘condition of release’ rules governed by the SIS Act.  This however, does not come without its pitfalls:

You can no longer implement the following types of insurances inside super:

*  Trauma cover
*  Agreed value Income Protection
*  Own Occupation TPD

Because of these restrictions, you may have to fund portions or entire personal insurance policies from your own pocket.

On the upside this new ruling will reduce a lot of stress at claim time as it sets expectations and makes the process more black and white, rather than rainbow coloured.  The new legislation changes also respect insurances implemented prior to 1 July 2014, you just have to be aware that your super trustee may stop or reduce the claim payable to you, holding any ineligible funds that don’t meet a condition of release inside your super.

We think the legislative changes are a positive move as the point of personal insurance is to protect you and your family financially, in the event of a medical tragedy such as death, or major injury / illness.  Any simplifications made to the claims process is always welcomed as it reduces stress and minimises time wasted during an already stressful time for both the claimant and their loved ones.

If you want to know more or if you want a review of your insurances whether you’re a JBS client or not, give us a call and we can chat further.


Create | Protect | Enjoy – Moving from the UK no longer allowed

Ever lived and worked in the UK but decided to settle in Australia? Well, you probably have some superannuation in the UK – what they call a pension fund. For a number of years, rules have allowed the transfer of these funds to Australia to make the management of your retirement funds an easier task however laws in the UK are changing which will mean that this option is no longer available. There is currently a proposal by the UK Government to ban the transfer of final salary pension benefits from public sector schemes. Legislation is currently being drafted for the change to take effect in April 2015. The change has come about as funded defined benefit schemes play an important role in funding long-term investment in the UK economy, which the Government does not want to put at risk by allowing the money to leave English shores.

What are some of the benefits of transferring to Australia? Investment Choice – you make the decision on where your funds are invested to make the most out of your money;

Death Benefits – (assuming the funds remain in superannuation or pension accounts) the full balance at the time of your death is payable to your beneficiaries or your estate (tax may apply) whereas funds are usually reduced or not able to be transferred to another on your passing if the money remains in the UK;

Tax benefits – the funds that are transferred, come in line with Australian superannuation tax rules, with returns taxed at 15% while in accumulation phase and then tax-free in pension phase. Benefits are paid out concessionally taxed prior to age 60 and tax-free from the age of 60.

Lump sum payments – you can take up to 100% of your superannuation out if a condition of release is met (UK tax may apply if within 5 years of being a tax resident). This is restricted to 15% in the UK otherwise additional penalty tax applies.

What are some of the drawbacks of transferring to Australia? United-Kingdom Lifetime pension – some UK pension providers will pay a pension for your lifetime. In Australia, this type of pension is no longer available.
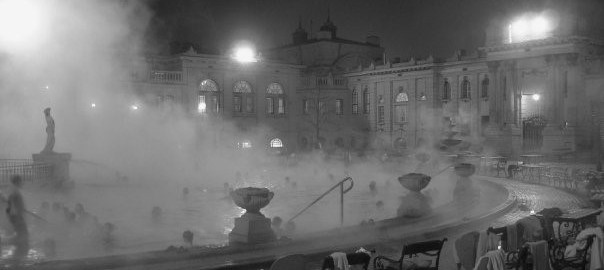
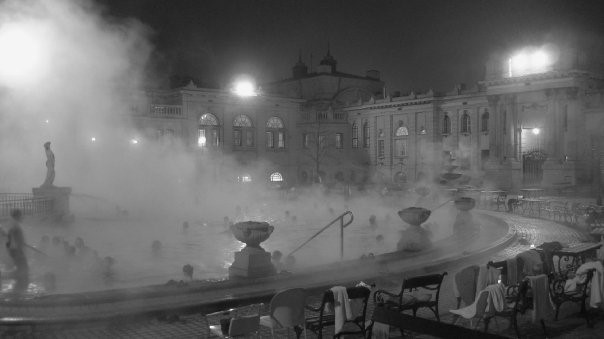
Exchange rate – the transfer of funds will also mean a conversion in money from pounds to Australian dollars which may mean a reduction in the value of your funds.

Growth not taxed – the growth in your UK pension is not taxed but if you transfer to Australia the growth from the date you became an Australian tax resident until the transfer is taxed at either 15% or your Marginal Tax Rate depending on your election.

QROPS – the provider receiving the transferred funds has to be a QROPS registered provider and report back to the UK any withdrawals or changes to your account for a period of 10 years after the transfer. In addition, if you consolidate with your other Australian super, any withdrawals from the fund will first be considered to be taken from the UK transferred funds.

What are the main things to consider when transferring a UK pension to Australia? Moving your pension funds from the UK has major implications that should be fully investigated and understood before a transfer is commenced to ensure that it is right for you because once it’s done, you can’t go back. Some of the main things to consider when looking at a pension transfer to Australia include:

*  you must have permanently left the UK with no intention of returning there.
contribution rules still apply and you cannot transfer in excess of the fund cap – currently $540,000. *please note that JBS may be able to help if your UK funds would breach this limit.
*  your UK pension must not have commenced paying a pension
be an Australian resident for tax purposes and have a TFN
if you transfer your funds within six (6) months of becoming an Australian tax resident, no tax is levied on the transfer to Australia.
*  if you transfer your funds outside six (6) months of becoming an Australian tax resident, tax is levied at a rate of 15% on the growth component since becoming a tax resident if you elect to pay it within your super.
*  if you transfer your funds outside six (6) months of becoming an Australian tax resident, tax is levied at your marginal tax rate on the growth component since becoming a tax resident if you wish to pay it personally or if you still have other UK pension funds remaining in the UK.
*  how you elect to have the growth component taxed will determine how much of the transfer will be counted towards your contribution caps. It is critical that this is done correctly to minimise the likelihood of an excess contribution.

What does this mean for those with UK Pensions?

You still have time to transfer your UK pension to the Australian Superannuation System if you want to or if it is right for you however time is running out. With a rush to action UK pension transfer, the usual six month wait to get the relevant information from the UK is extending further by the day. If you want to consider your options in relation to a possible transfer, you should either contact your UK pension provider directly and ask for a valuation as well as retirement projections that provide you with the final benefit options available to you at retirement such as a lifetime pension, or alternatively contact our office and we can get the information and do the sums for you to ensure that it’s the right move for your financial goals and current circumstances.


Adam’s Europe Trip

Coming from 40 degrees to being woken by the pilot announcing it was 4 degrees almost made me do a U-turn in customs. However, I am slowly settling back into the routine after an amazing 4 week break in Europe. I saw some amazing things and met heaps of intriguing people. I spent the majority of my break in Hungary and Malta and thought I would share some of the highlights.

We began in Budapest, the capitol of Hungary. It is an amazing and charming city, full of great food, awesome rooftop bars, Mongolian architecture and dainty markets. The city is small enough to walk if you are staying centrally or alternatively the public transport is cheap.

They have the amazing Szechenyi Public Baths (see photo below) which are frequented by both locals and tourists. There are an array of pools, spas, sauna’s and steam rooms all varying in temperature. You can also book yourself a massage with a fully trained physiotherapist for a few dollars!

Baths

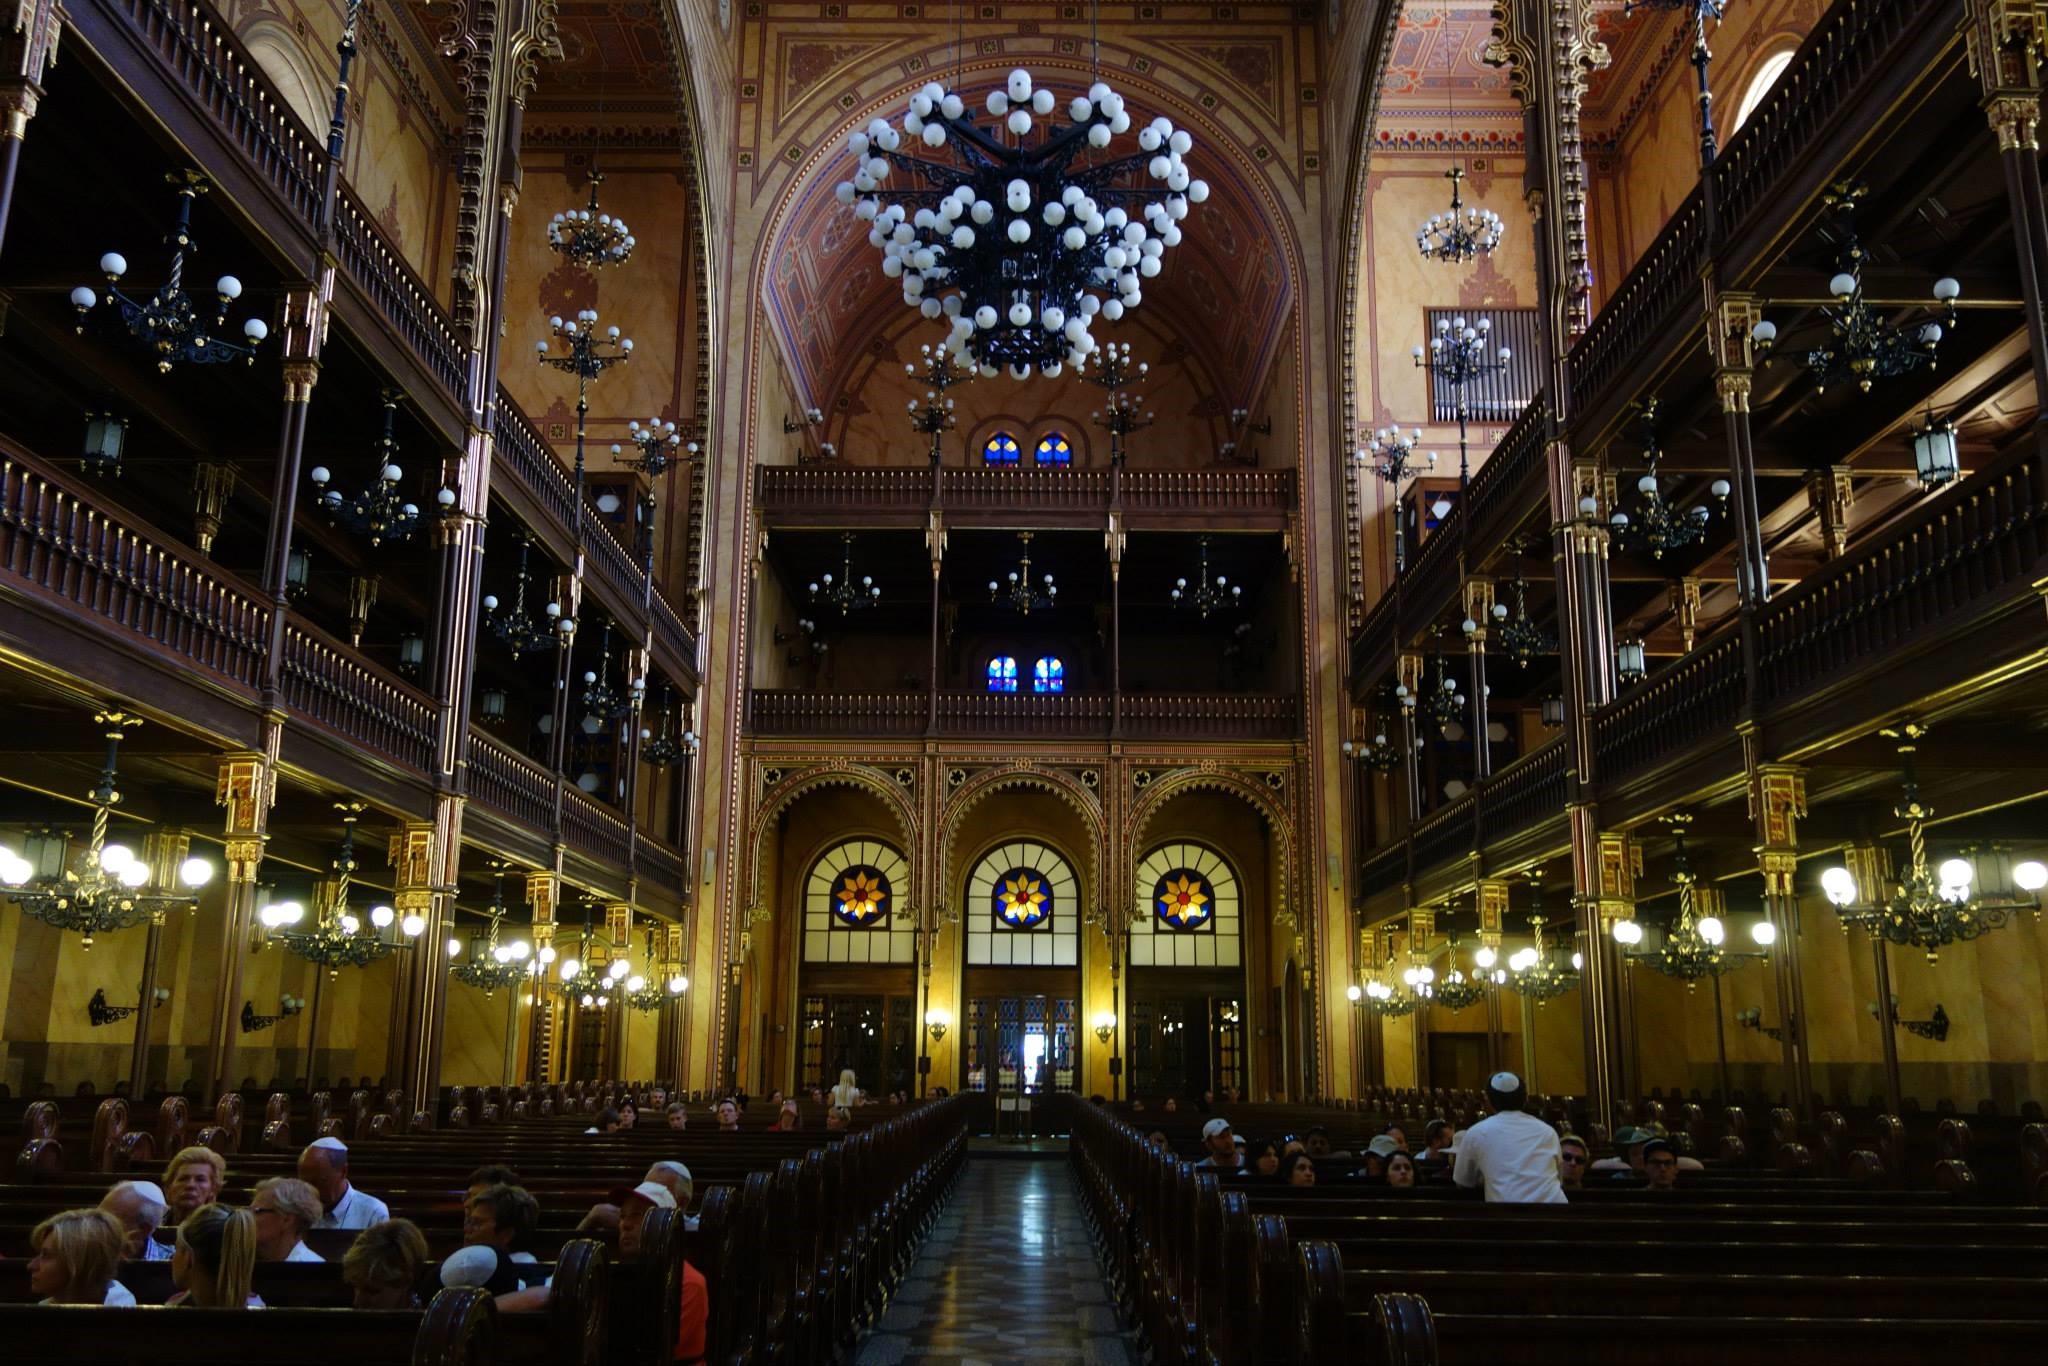
We also visited the old synagogue which is the most amazing and intricate building of its type I have ever seen in the world (photo below)

Building

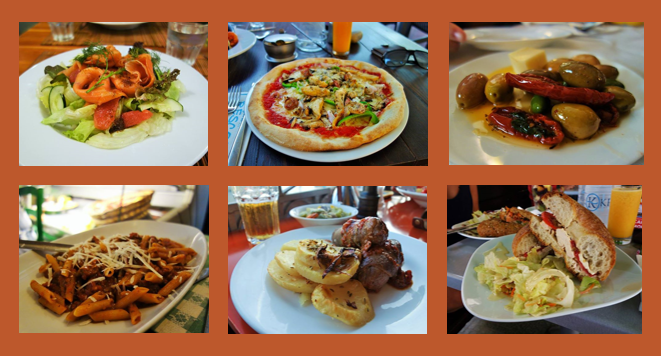
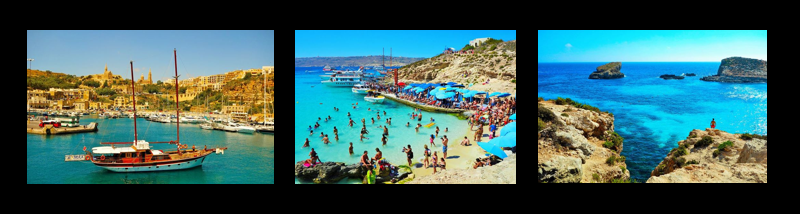
After we had eaten enough goulash we ventured into the Mediterranean Sea to visit Malta. It is a tiny island measuring 28km across and is almost 100km directly below Sicily. Malta quickly became one of my favourite places that I have visited in Europe. You can spend between 7 and 10 euro per meal and be absolutely stuffed with fresh and tasty produce.

Food

They have amazing architecture and history there, including both pebble and sand beaches which makes it the perfect place to do a little bit of touristy stuff and also completely relax. The island has an intricate network of busses; tickets cost 1.50 Euro for the entire day which makes it easy to get around. We did a day trip to the neighboring island of Gozo, where they have the oldest monolithic structure in the world (5500 BC) and also film scenes for Game of Thrones.   You can catch a ferry there from the main island which delivers you to this port (see photo).

On the way back from Gozo, you can detour via the Island of Camino which has the bluest water I have ever seen in the world, even clearer than the blue grotto in Capri. The fast boats cost about 10 Euro and run from 10 in the morning until 6 in the evening, they also take you on a quick tour of the caves around the island of Camino.

Malta

The trip was amazing and I have come back truly relaxed. I can definitely recommend visiting both Hungary and Malta, if you are considering a holiday there, send me an email at amckenzie@jbsfinancial.com.au and I will reply with some more detailed notes and tips.


Create | Protect | Enjoy – What are Franking Credits?

Ever wondered what a franking credit is? Well…it’s not what you get when you do a favour for your mate named Frank. (ha ha get it?) Franking credits are a useful little tool to help pay less tax or even boost up your investment returns.

What are franking credits and how do they work?
Franking credits, also known as imputation credits, are essentially credits representing tax that a company has already paid  (currently 30%) on its profits prior to a dividend being paid.

Basically franking credits stop double tax being paid on company profits as the tax paid by the company can then be passed to the shareholder.  So for example, your XYZ share that you own pays a dividend of $1.00 per share after tax. This means that they have already paid the 30%, so this $1.00 is actually $1.43 with $0.43 per share paid in tax. When you come to do your taxes, you get a credit for the $0.43 per share already paid so if your tax rate is 32.5%, you only need to pay the remaining 2.5% on the $1.00 per share dividend received.

Franking credits in superannuation franking credits explained white
In superannuation (accumulation phase), the tax rate is 15%, compared to a company tax rate of 30%. The 15% difference in tax payable, can be refunded to your superannuation account and further enhance the return achieved from your share investments.

Example
Michael holds his super through a SMSF. He has an investment of 500 shares in ABC company which paid a dividend of $3.30 per share. This equates to a lump sum dividend payment of $1,650. With this comes $707 in franking credits (30%). As he is in accumulation phase and only paying 15% on income earnt within the fund, his SMSF is eligible to receive a refund of $353.50.

Franking credits in pension phase
The other good news is that when you are in pension phase and paying 0% tax, franking credits received by your super fund are fully refundable even without taxable income in your superannuation. This means that your super can claim back all the tax already paid by the distributing company from the ATO.

With either a superannuation or pension phase account, you need to understand the structure of your superannuation investments as bundled share purchases like through a pool super trust may not necessarily give you the same tax credits.

Example
Sally has reached age 65 and retired. She now has a pension account with a retail pension provider. Within her balance she holds 1,000 shares in XYZ company that paid a dividend of $8.70 per share. This equates to a lump sum dividend payment of $8,700. With that comes $$3,728 in franking credits (30%). As she is in pension phase and paying no tax, her pension fund is entitled to a refund of the full tax paid ($3,728) which would be repaid into the cash account of her fund and will help to cover ongoing pension payments.

Franking credits can be a great added extra in returns alongside growth and income to boost the overall return. They should most certainly be a consideration when developing an investment portfolio for your retirement funds. If you want to learn more about franking credits or direct shares, don’t hesitate to contact one of the team members at JBS.


logo


SIGN UP TO OUR NEWSLETTER

* indicates required