Tag Archives: Insurance

Stepped vs Level Premiums

Personal insurance policies may have a large effect on our cash flow. One factor which dictates how much you pay is whether your insurance premiums are structured on a stepped or level premium. If you’ve ever held any form of personal insurance then you may have come across these terms, however have you ever wondered what the differences is between the two? When your personal insurance policy is initially set up, you have the option to choose whether to have the premiums set on a stepped or level structure.

 
Having your premiums on a stepped structure would generally mean you pay lower premiums initially compared to a level structure.  Stepped premiums increase annually with the added risk of a potential claim.  The downside however is that over time your stepped premiums will increase each year as you get older. This method may not be desirable to some as the premiums may become too expensive to sustain over time.  In certain circumstance, stepped premiums are more favourable.

 
For example a 25 year old male may not be able to afford insurance premiums on a level structure, however in several years’ time he may be earning a larger income and thus be able to afford level premiums. So in the meantime he can put in place his personal insurance policy on stepped premiums to ensure he’s covered and once can he can afford to pay level premiums, he can change the premium structure.

 
Or you may have to take out an additional loan for a short period of time (say 5 years) and you can then ensure you have sufficient insurance to cover this debt for just the 5 years and cancel the policy once the debt is repaid.

 
A level premium is the second option you have and it calculates the risk over the life of the policy (assuming it is held to the expiry of the policy – age 65 and above depending on your policy) and spreads the cost of this risk.  Although initially more expensive to set up, insurance policies on a level structure will not increase over time (excluding any CPI increase).  A disadvantage to having level premiums is it may have a larger impact on your cash flow initially, however over time the savings will catch up.

 
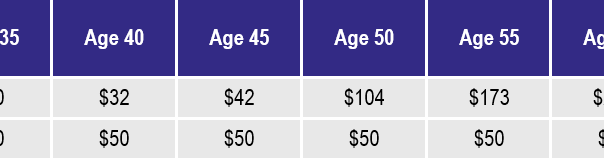
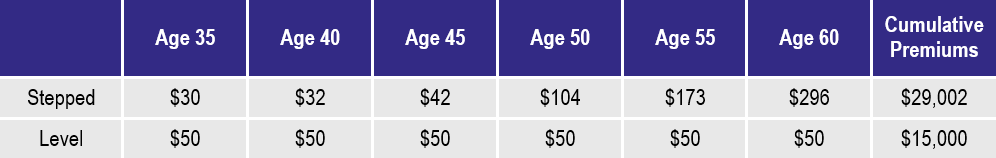
The following table is an example of a 35 year old male with $500,000 of death insurance.
CPE Image

*Please note premiums are shown in months. The above table is only an example, for personalised quotes please contact your adviser.

 
As shown above, stepped premiums are initially cheaper, however over time becomes much more expensive.  In the above example the insured person from age 35 to 60, will have paid $14,002 more under stepped premiums compare to a level structure.

 
Stepped and Level premiums are only one factor to consider when reviewing your insurance needs tailored to your needs. So if you’re interested to know more, please contact JBS for further details and advice.


Interest Rate Considerations

In the late 80s interest rates peaked at 17% which made home ownership out of reach for most people and hard to cover for those that had them. We move forward to today and the Reserve Bank Cash Rate is at a very low 2.25% with the last rate rise occurring in November 2010.


While this isn’t great news if you’re thinking of investing into bank deposits or fixed interest investments as returns are low, it does open up opportunity for people to review their mortgage, other debts and financial planning affairs in general.


Should_You_Refinance_To_Settle_Your_Car_Loan_Personal_Loan_Early

Some of the main considerations could be:

–   Obtaining a low rate mortgage that still provides the benefits that you need or utilise. If you refinance to the lowest rate loan you could end up paying a higher interest rate on your credit card and may not be an appropriate strategy or beneficial for you

 
–   There are lenders outside the major 4 banks. While many of us complain about the big 4 making massive profits, we also like their security. You can consider options outside the banks and look at credit unions, lending societies, and other lending institutions.

 
–   Reducing your mortgage interest rate and continuing to make the same level of repayments could see you reducing the length of your loan which means interest savings. But, are there restrictions on how much you can make in additional payments? Do you have a redraw facility in case you need to access the funds?

 
–   Credit card interest rates are high and can be up to 20% so consolidating debt may be a way to go, especially if you can reduce that down to say a mortgage rate of around 5%. But beware because if you don’t make additional payments to cover the consolidated funds, you are extending the term of this debt and could end up paying higher interest over the life of the debt.

 
–   Margin lending becomes more appealing with lower interest rates however any strategy that includes debt, should also have contingency plans. Can you still afford it if interest rates increased by as much as 3%? Do you have relevant insurances in place to ensure that can cover your obligations if you can’t work?

 
–   Returns on cash and fixed interest investments become lower and shares become more appealing however you need to consider the risks involved. Chasing returns rather than investing into a diversified portfolio could see a decline in your balance outside what you are comfortable with.

 
–   Be careful with your spending, with additional funds in our pocket due to lower interest rates, it is tempting to spend more. Maybe consider making additional repayments of debt, additional savings or additional super contributions to ensure that the additional money available in your cashflow isn’t blown.


While you may think that you’re personal situation hasn’t changed, the world around you is. Interest rate rise and fall, economic markets changes and legislation is amended, which is why you should be regularly reviewing your financial position. If you haven’t had a review of your financial plan lately, make sure you give the team at JBS a call to make an appointment.


Create | Protect | Enjoy – Movember, Supporting Men’s Health

Movember is an annual event  involving the growing of moustaches during the month of November to raise awareness of men’s health issues, specifically prostate cancer and other male cancers.  The fact this event attaches so much attention and is encouraged by the medical profession show the seriousness these health issues have on families.Mo

The facts:

  • Prostate cancer is the most commonly diagnosed cancer in Australian Men (20,000+ new cases per year)
  • 1 in 8 Australian men (1.3 Million) experience depression at any given time.
  • Every hour, more than 4 men die from potentially preventable conditions in Australia.

There are many complex reasons for the poor state of men’s health which include: 

  • Men not openly discussing their health and how they’re feeling
  • Reluctance to take action when men don’t feel physically or mentally well
  • Men engaging in risky activities that threaten their health
  • Stigmas surrounding mental health
  • Men are less likely than women to seek help for health concerns, and also less likely to use health care services


It is important that families are adequately protected to combat the financial impact that Prostate cancer and other illnesses impose.  This financial stress can be removed through implementing appropriate levels of insurance, an area JBS Financial Strategists can assist with.

For more information regarding men’s health issues click here.


Create | Protect | Enjoy – The Spring Carnival Highlights Australia’s Risky Nature

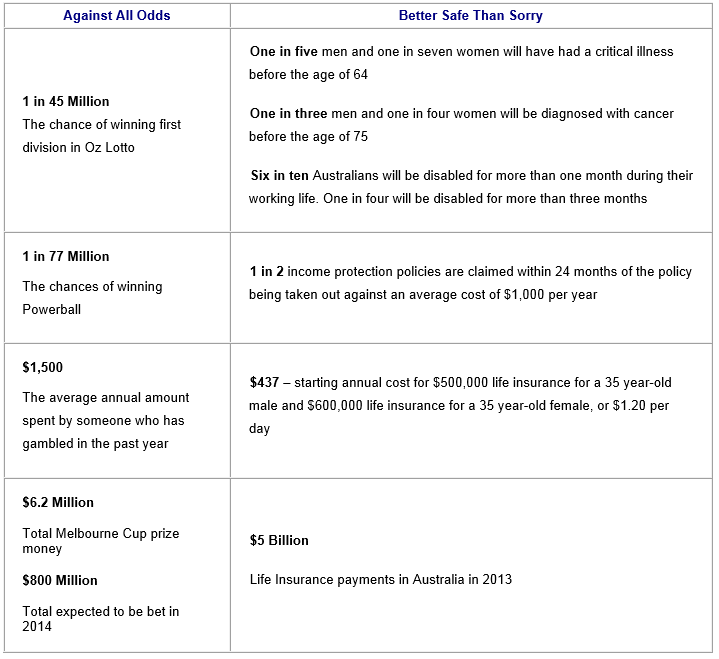
Approximately $800 million+ was wagered on Melbourne Cup Day.  It is part human nature to trust in luck or a big windfall such as winning the ‘big one’ at the Melbourne Cup or the lottery, and for most people it’s just good fun.  But statistically we know this is highly unlikely to happen.  We also know that a high proportion of people will suffer a significant health event throughout their working life resulting in their income stopping.

There is a greater chance of suffering a heart attack than winning the Melbourne Cup trifecta.  In fact, the confronting news is if you buy a tattslotto ticket the day before the draw, studies show you have a greater chance of dying before the lottery is drawn than winning it.

The challenge is to make sure we take the ‘gamble’ out of things that really matter, like protecting our family in the event we become sick / injured and are unable to work to ensure we can continue to pay the mortgage and living expenses.

What are the Odds?

table2

A lack of financial preparedness can have significant impacts down the track.  No one wants to find themselves in a situation where they can no longer support themselves financially.  It is about making your own luck rather than simply hoping for the best.

If you wish to discuss your risk protection options further, please contact one of the advisers at JBS.


Create | Protect | Enjoy | Insurance is a Super Benefit

Australians love being able to enjoy life with their friends and family, travel the world and drink till the sun comes up.  In order to do so we earn, save, invest, borrow and do whatever is necessary to accumulate enough funds to enjoy the finer things in life.  For a lot of Australians, taking financial risks is simply a part of everyday life; trading stocks, gambling or buying investment properties.

Today, over 80% of Australians are taking the biggest financial risk and not protecting their biggest asset, which is their own ability to earn money.  It’s relatively easy to earn it, it’s easier to burn it and apparently 80% of us think it’s too hard to protect.

In 2012, the Australian Life Insurance Industry paid out $4.4 billion in total claims.  This stat isn’t meant to highlight the fact that insurers do payout, but highlights the fact that tens of thousands of Australians in 2012 died, suffered from a terminal illness, were diagnosed with a critical illness or suffered a serious injury or illness stopping them from earning their most valued asset, income.

There are several Personal Insurance types that can assist in protecting you financially such as Life, Total & Permanent Disablement (TPD), Trauma and Income Protection.  Each serves its own purpose; to provide financial aid in the event the proverbial dung hits the fan.  Yet 80% of us think…
•    “It’ll never happen to me”, $4.4 Billion says otherwise.
•     “I’m sure it’s in my Super”, maybe, but is it enough?
•    “It’s too expensive”, where else can you get $4.4 billion?

Although Super is a convenient funding mechanism for Personal insurance it doesn’t come without its difficulties, especially at claim time.

When you hold Insurance within a suKFC Witness protectionper fund, the super trustee effectively owns your insurance and it is their responsibility to ensure any insurance payment made into the fund meets a ‘condition of release’ before they can be withdrawn from your super fund.  These conditions are set by the Superannuation Industry (Supervision) Act 1993 (SIS Act) and includes insurance claim benefits.

In the event an insurer pays out a claim, the benefits (money) are paid to the super trustee, not you or your beneficiaries.  It is then up to the trustee to determine if you meet a ‘condition of release’ before paying you the funds.  So a few legislative changes have been introduced, effective 1 Just 2014 to align and hopefully resolve the double handling of claims.

The old way:
Pre 1 July 2014, if you implemented Insurance inside a super fund, in order to get the proceeds of a successful insurance claim in your hands, you were required to satisfy two separate conditions, as mentioned above:
1.    The definitions under the insurance policy set by the insurance company to pay out the claim; and
2.    The superannuation ‘condition of release’ rules set by the SIS Act.

Unfortunately for some people who successfully claimed on their insurance, this made the process difficult.  Just because the insurance company said, “yes you can make a claim”, didn’t necessarily mean your super fund would hand over the cash.

The simple fact of the matter was a misalignment if conditions existed.  Insurers were approving claims, paying the benefits to the super trustee, but the super trustee was holding the funds inside the members super account because a ‘conditions of release’ was not met.

The new way
From 1st July 2014, the aforementioned conditions must now mirror one another, meaning that definitions of insurance policies available under super are much stricter.  They must reflect the ‘condition of release’ rules governed by the SIS Act.  This however, does not come without its pitfalls:

You can no longer implement the following types of insurances inside super:

*  Trauma cover
*  Agreed value Income Protection
*  Own Occupation TPD

Because of these restrictions, you may have to fund portions or entire personal insurance policies from your own pocket.

On the upside this new ruling will reduce a lot of stress at claim time as it sets expectations and makes the process more black and white, rather than rainbow coloured.  The new legislation changes also respect insurances implemented prior to 1 July 2014, you just have to be aware that your super trustee may stop or reduce the claim payable to you, holding any ineligible funds that don’t meet a condition of release inside your super.

We think the legislative changes are a positive move as the point of personal insurance is to protect you and your family financially, in the event of a medical tragedy such as death, or major injury / illness.  Any simplifications made to the claims process is always welcomed as it reduces stress and minimises time wasted during an already stressful time for both the claimant and their loved ones.

If you want to know more or if you want a review of your insurances whether you’re a JBS client or not, give us a call and we can chat further.


logo


SIGN UP TO OUR NEWSLETTER

* indicates required